The Shift From CSR To Compliance
For years, reporting your carbon footprint was a “nice-to-have” part of your Corporate Social Responsibility (CSR). As of 2026, the UK is moving toward more formalised sustainability reporting within the financial reporting framework. If you are a large business, your carbon footprint is no longer just an environmental metric—it is a legal financial disclosure.
The “Supplier” Requirement: Scope 3
The most significant change is the requirement to report Scope 3 emissions. This includes emissions across your wider value chain, such as suppliers, outsourced services, and the technology you use.
When you use an AI model, whether it’s for customer service, coding, or data analysisthat AI lives on a server. Those servers require vast amounts of electricity and water for cooling. Under new reporting rules, if you use an AI vendor, their carbon footprint contributes to your Scope 3 emissions.
It is also worth noting that not all AI usage has the same carbon impact. Factors such as model size, usage patterns, and provider efficiency all play a role, and many providers are actively working to improve energy efficiency and increase their use of renewable energy.
Who needs to report, and when?
In the UK, the requirements are primarily based on the size of your business. Under the Streamlined Energy and Carbon Reporting (SECR) framework and the newly emerging UK Sustainability Reporting Standards (UK SRS):
| Business Size | Criteria (Must meet 2 of 3) | Requirement |
|---|---|---|
| Large Companies | 250+ employees, £36m+ turnover, or £18m+ balance sheet | Mandatory reporting of Scope 1 & 2; S Scope 3 reporting is increasingly expected under emerging standards such as UK SRS (aligned with ISSB), although requirements are still evolving. |
| Quoted Companies | Any size (if listed on a stock exchange) | Mandatory global energy use and GHG emissions. |
| SMEs | Below the thresholds above | Currently voluntary, but often required by larger clients to fulfill their Scope 3 data needs. |
Does it matter if the AI company is overseas?
 Yes…and being overseas actually compounds the risk.
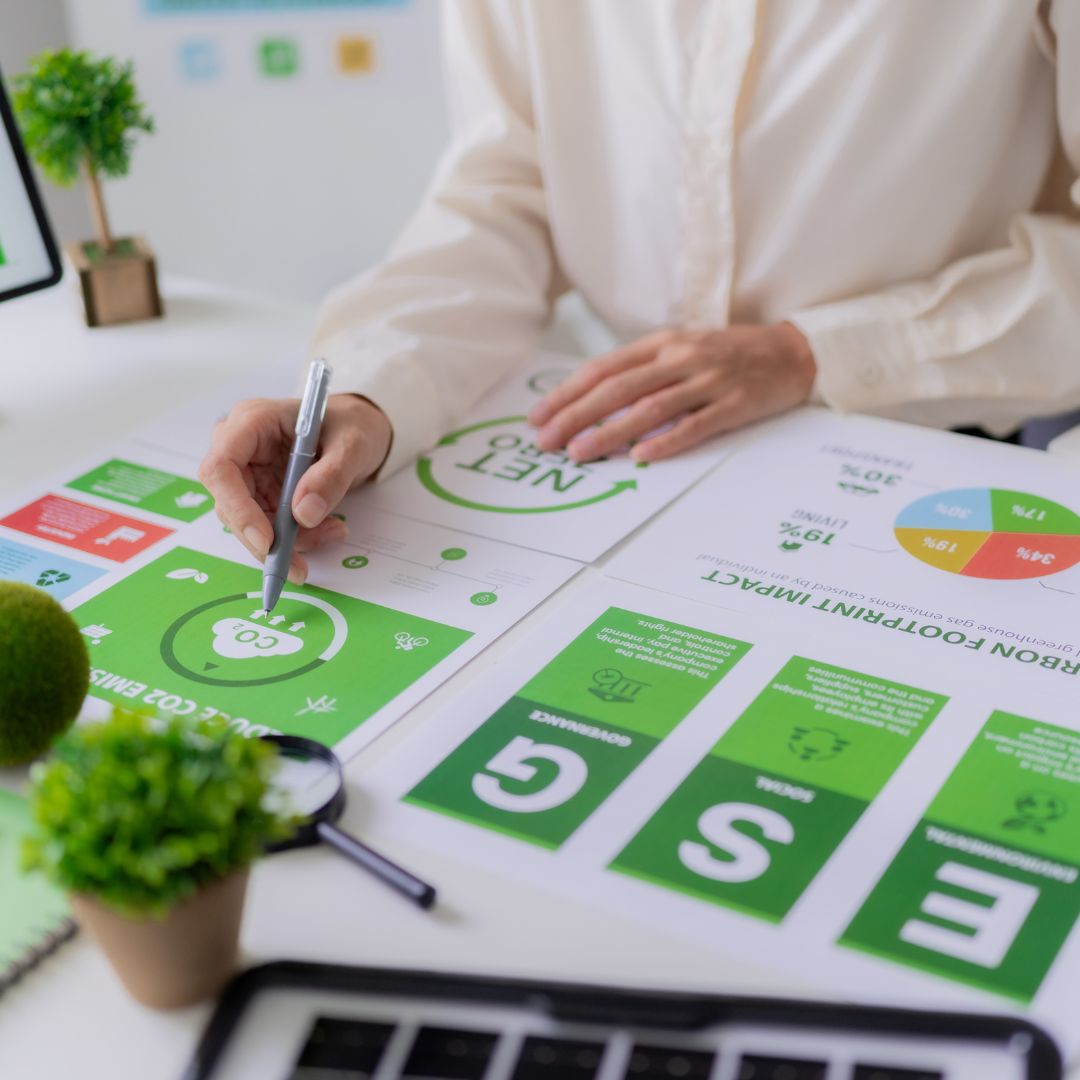
In the regulatory landscape of 2026, supply chain emissions are not limited by geography. If your business reports in the UK (under the new UK SRS standards) or the EU (under CSRD), you are legally responsible for the “imported” emissions of your tech stack.
For example: when you use a US-based AI giant such as, OpenAI, Google, or Microsoft you are incorporating the carbon intensity of those data centres into your own Scope 3 disclosures.
Conclusion
When choosing an AI partner, don’t just ask about their Application Programming Interface or their price ask for transparency around their carbon impact (for example, carbon intensity per query or similar metrics where available). . Your finance team will thank you later.
Increasingly, AI selection is not just a technical decision, but a procurement, finance, and risk consideration.